If your home sits in Eastern Washington or another higher-risk area, there’s a three-digit number you may never see, but it can decide whether you can keep your insurance, and how much you’ll pay for it. It’s your property’s wildfire risk score.
The August 2026 wildfires that swept through Spokane, destroying roughly 700 homes and forcing about 65,000 people to evacuate, were a stark reminder of how fast this can change. Homeowners who understood their risk score and their coverage options beforehand were in a far better position than those who found out during an active fire.
What a wildfire risk score actually is
A wildfire risk score is an insurer’s estimate of how likely a specific property is to be damaged by fire. Most insurers don’t calculate it themselves, they buy it from modeling companies (the best known is Verisk’s FireLine) and feed that score into their decision to cover you, renew you, and what to charge.
The score usually lands on a scale or in tiers like Low, Moderate, High, and Extreme. Above a certain line, an insurer may charge much more, require specific fire-prevention work, decline to renew you, or decline the home entirely. Washington lawmakers have taken notice: a state Senate bill (SB 5928) would require insurers to disclose these wildfire risk scores directly to homeowners, rather than leaving them a mystery.
Three things drive almost every model:
- Fuel: the vegetation around the home. Dense brush and trees close to the house raise the score; cleared, irrigated space lowers it.
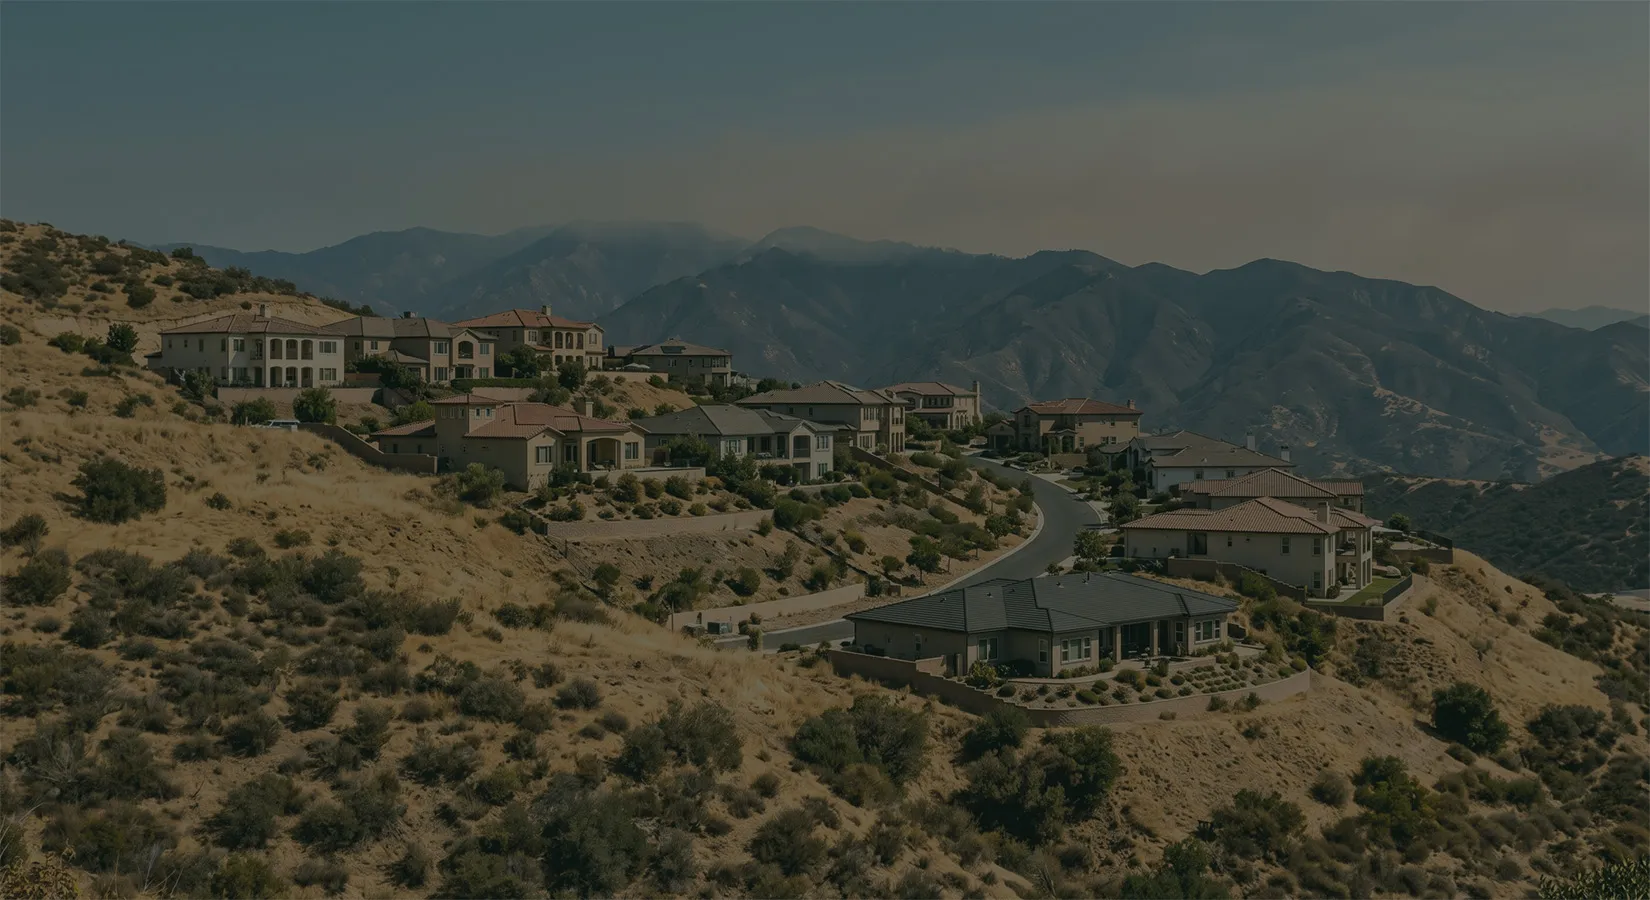
- Slope: fire moves faster uphill, so a home on a steep grade scores worse than the same home on flat ground.
- Access: narrow, single-exit roads are harder to defend and evacuate, which models penalize.
Notice what’s not on that list: how well-maintained or updated your home is otherwise. A beautifully kept home can still carry a high score because of the terrain around it.
Why this can surprise homeowners at renewal
The risky moment isn’t when you first bought the home, it’s at renewal, when a carrier reruns its models and your score has crept into a worse tier, or a nearby fire has pushed the whole area’s risk profile up. That’s when non-renewal notices show up, often with little warning.
How to check your risk before a notice arrives
-
Look up the public risk view. Free tools like the First Street “Risk Factor” (built into many real estate listings) and the Washington State Department of Natural Resources’ Wildfire Hazard and Risk Mapping tool give you a directional read on your specific property.
-
Ask your current insurer what’s changed. If your premium jumped or you got a non-renewal notice, ask directly whether your risk score or tier changed.
-
Get a real quote before you need one. A licensed broker can check several carriers’ appetite for your home in a day, well before fire season puts pressure on the whole market.
-
Know the backstop. The Washington FAIR Plan exists for homes the standard market won’t cover. It’s more expensive and more limited (actual cash value only, capped at $1.5 million), but it keeps a home insurable when nothing else will write the policy.
What you can do about a high score
A high score doesn’t mean your home is unsafe or uninsurable, it means insurance takes more planning and may cost more. Fire-prevention work genuinely helps: clearing defensible space, replacing a wood-shake roof, installing ember-resistant vents, and boxing in eaves are the kinds of upgrades insurers increasingly reward. Keep receipts and documentation for any of this work; it’s real ammunition when your broker is shopping your renewal.
The takeaway
Treat your wildfire score like you’d treat a home inspection: check it before renewal season, not after a non-renewal notice arrives, and talk to a broker early enough to actually have options.
Ready to see where you stand? Get a quote in minutes from an independent broker who knows the Washington market.